Purchasing a 2nd Home?

So, you would like to buy a 2nd Home?
Living in a desirable resort or other location could be a dream come true; nevertheless, it is important not to get too distracted by the beauty of the environment.  Ask yourself the difficult questions such as, “Why do I really want to own a house here?”  or, “What would I do with the house after the purchase?”.

Where Should You Buy?
When dealing with any real estate transaction, location is the first, second and third most important consideration.  Although, be sure to think about the local resale values, economic trends, tax rates, schools, health care, and other additional factors.  Ultimately, the ideal location for your second home will depend on your reasons for desiring a second home.  Here are some thoughts on a second home:

  1. 1. Spend more time in a favorite vacation spot
  2. 2. Invest in property that could produce income and appreciate
  3. 3. Rent to tenants short-term, allowing you to visit frequently
  4. 4. Fix it and flip it

If you think you might want to move to a specific location, you should consider renting in the area first.  This will allow you to “test out” the area, and experience “life” at the location before you dive into a massive purchase.  You would understand the rhythm of the area; find out where your ideal location would be, test out the best golf courses, and find near-by activities.

How much can you afford?
Buying a second home is a major commitment.  You must consider a mortgage, the expenses of maintaining a home, paying taxes, management fees, and insurance; these things can all add up.  If buying into a community or a condo, you should know about the HOA and maintenance fees.  Insuring a property with a pool or near the beach will increase the carrying costs of the second home (consider floodplain).   
Some second home buyers can purchase with cash, while others will need to qualify for a second-home mortgage.  Mortgage financing will be calculated in addition to mortgage debt on your primary home.
It would be wise to make a down payment of 10% – 20%. You must meet credit standards, debt-to-income requirements, and provide documents for income and asset verification.  Mortgage rates are very low; although, they are slightly higher on a second home.  A mortgage lender is helpful.

Consider the Tax Implications.
If you live in the home, you can deduct the property taxes. The new limit for State & Local taxes is $10,000 per tax return.  Recall that the Tax Cuts and Jobs Act caps the mortgage interest deduction at $750,000 of total mortgage debt.
According to the IRS, second homes have different rules for investment properties than vacation homes; so, consult your tax accountant.
When considering the purchase of a second property, it is important to think about the taxes, insurance, maintenance, furnishings, property management, and repairs which come along with owning a second property.  Contact Schenley Capital Inc. before purchasing a second home to see how it fits in with your overall financial picture.
(412)-749-9256
417 Walnut Street
Suite 200
Sewickley, PA 15143
Written by
Elizabeth Genter

529’s

     From the day a child is born, every family would love to plan and save for their child’s future. Paying for your child’s education can seem out of reach with college and trade school tuition constantly rising. Luckily, there is an investment plan called a 529 that can help make those big dreams become a reality!

     A section 529 plan is a savings plan designed to promote saving for your children’s college or trade school tuition.

     College savings plans allow the person who contributes to the account, the account holder, to save for their beneficiary, the future college or trade school student. The 529 account is tax deferred, meaning that the contribution into the 529 are not deductible, (a small portion is for the state of PA). Earnings grow tax free and will not be taxed when you take out money for college expenses. All earnings, income, and gains on the investment inside the 529 accounts are not subject to income tax or a 15% capital gain tax.

     A parent, grandparent, or family member can initiate a 529 for the child.  While the account is called a “college savings plan”, the plan does not exclusively cover colleges; but will cover trade school’s tuition, art schools, or a semester abroad, room and board costs, books, fees, and a computer. 

      One great aspect of a 529 is that the earnings are not subject to federal taxes, if, the withdrawals are used for college or trade school tuition and other college related expenses. If you withdraw from your 529 account and do not use the funds for college or trade school based expenses, you will be subject to income tax and an additional 10% federal tax penalty on your earnings. A 529 can impact federal financial aid for a student as well. When a student has a 529 plan, this usually greatly reduces the participation amount, if any, that will be awarded to a student with federal financial aid. As of 2006, assets held in either 529 plan will be counted as parental assets when filling out a student’s financial aid forms. Students with a carefully planned and funded 529 plan may not even have the need for financial aid, as their investments will work for funding their entire education.

     Speaking to a qualified investment advisor with a solid knowledge of 529’s is every parent, grandparent, aunt, uncle, or other family members safest decision.

An advisor would be able to guide you with proper planning to benefit your future college bound student!

   written by: ||Beth Genter – President||

Schenley Capital Breakfast Event Recap

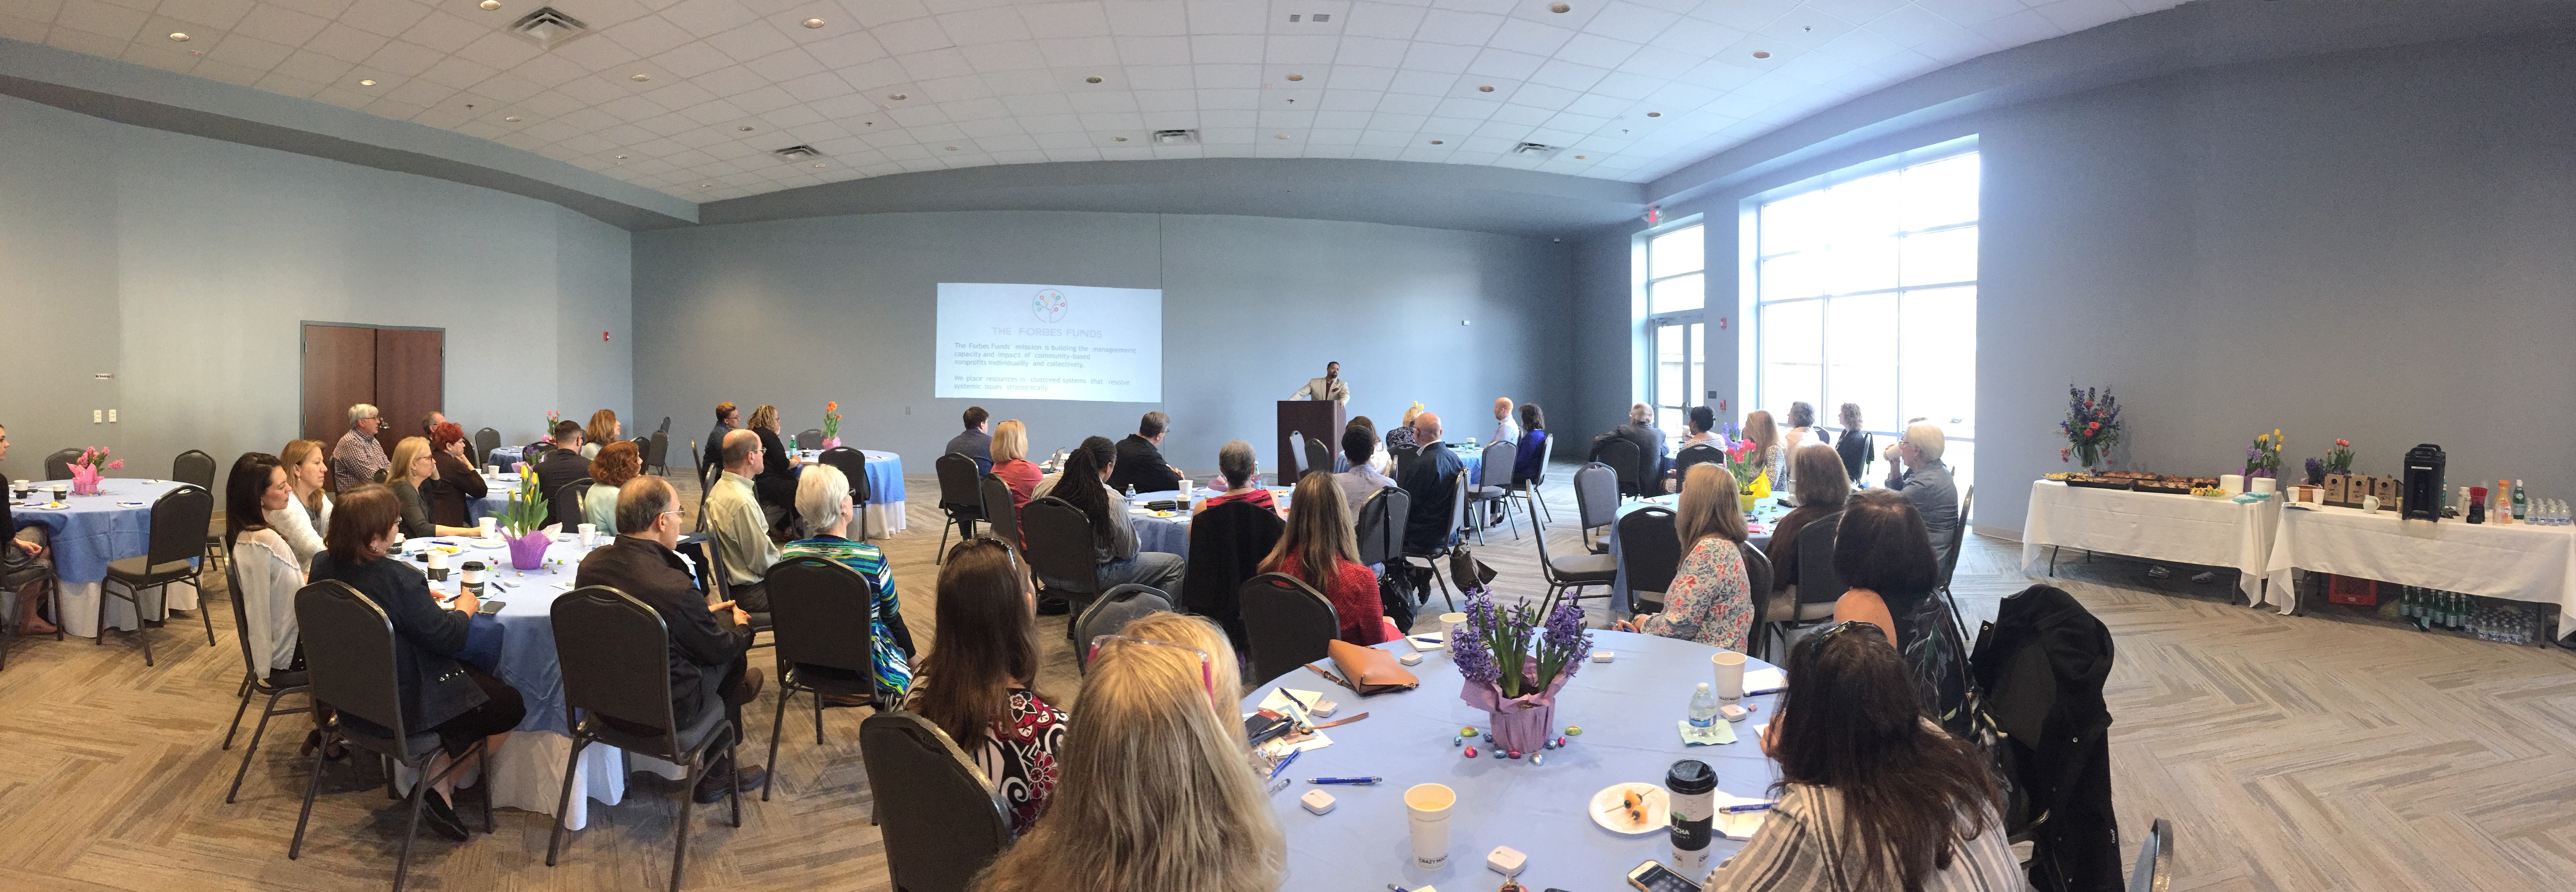
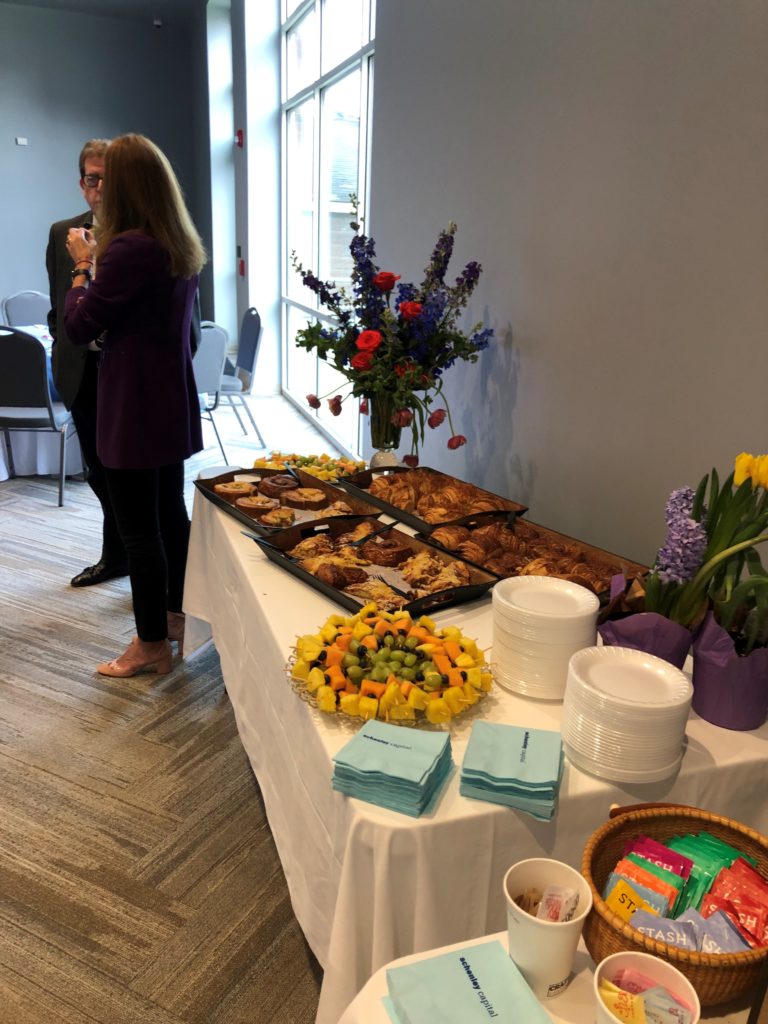
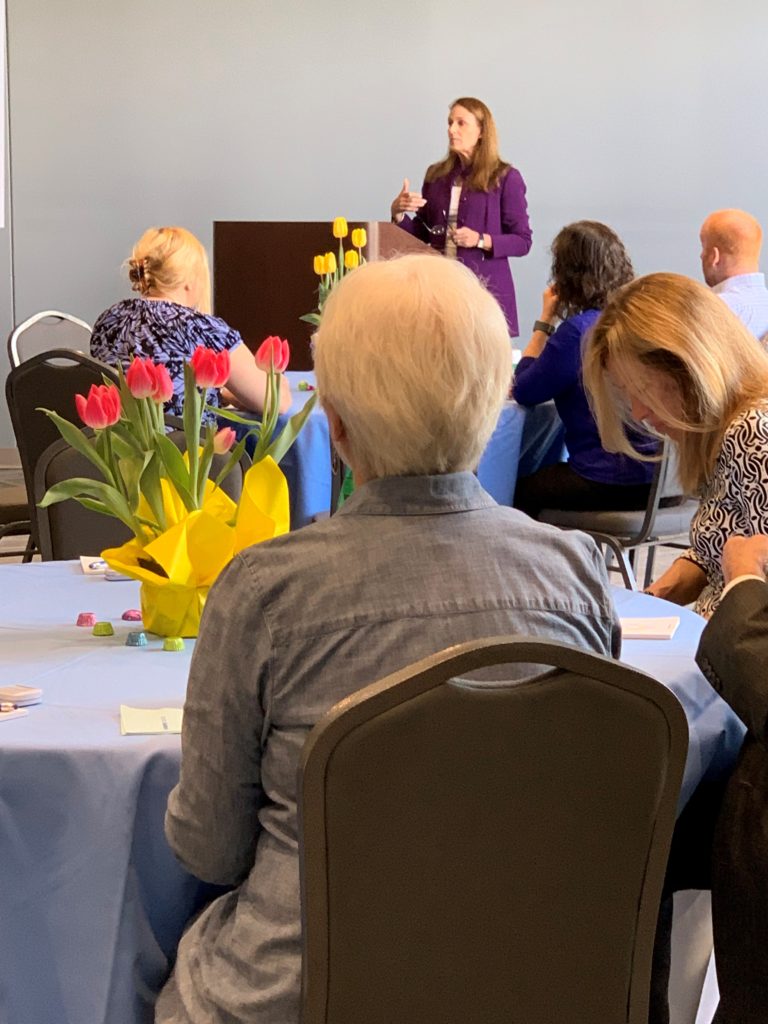
Schenley Capital, Inc. sponsored their 2nd annual breakfast speaker in Sewickley on April 18th, 2019.  They hosted this event for the Sewickley Non-Profit Consortium (SNPC) and invited additional regional non-profit organizations to the breakfast event.

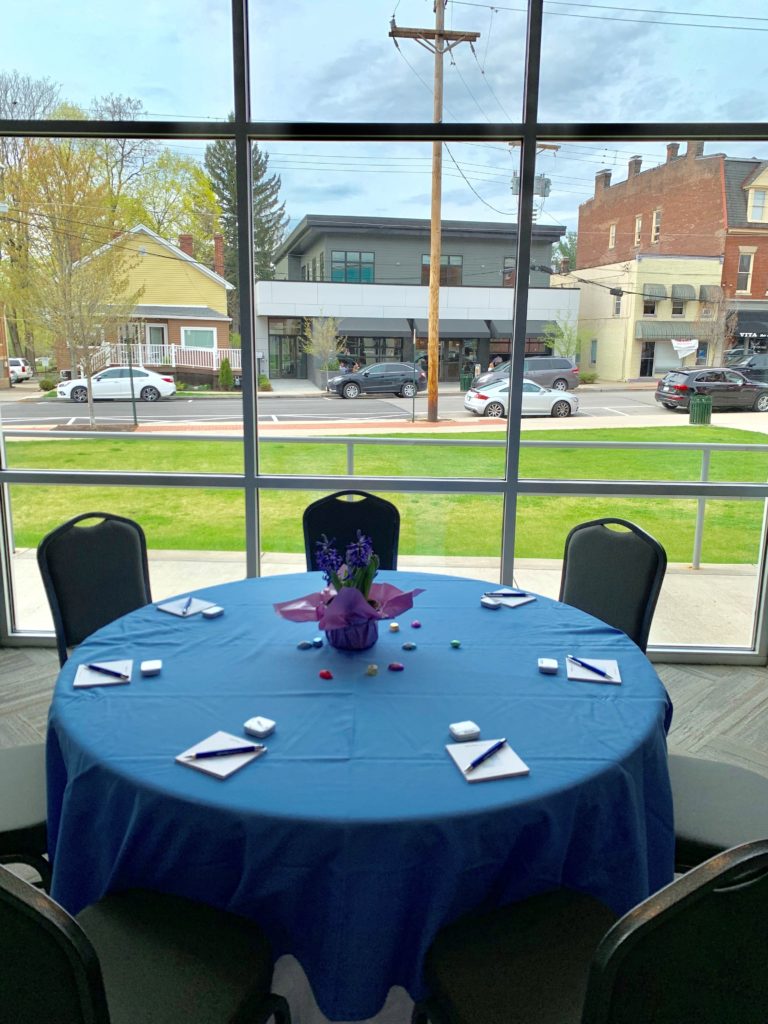
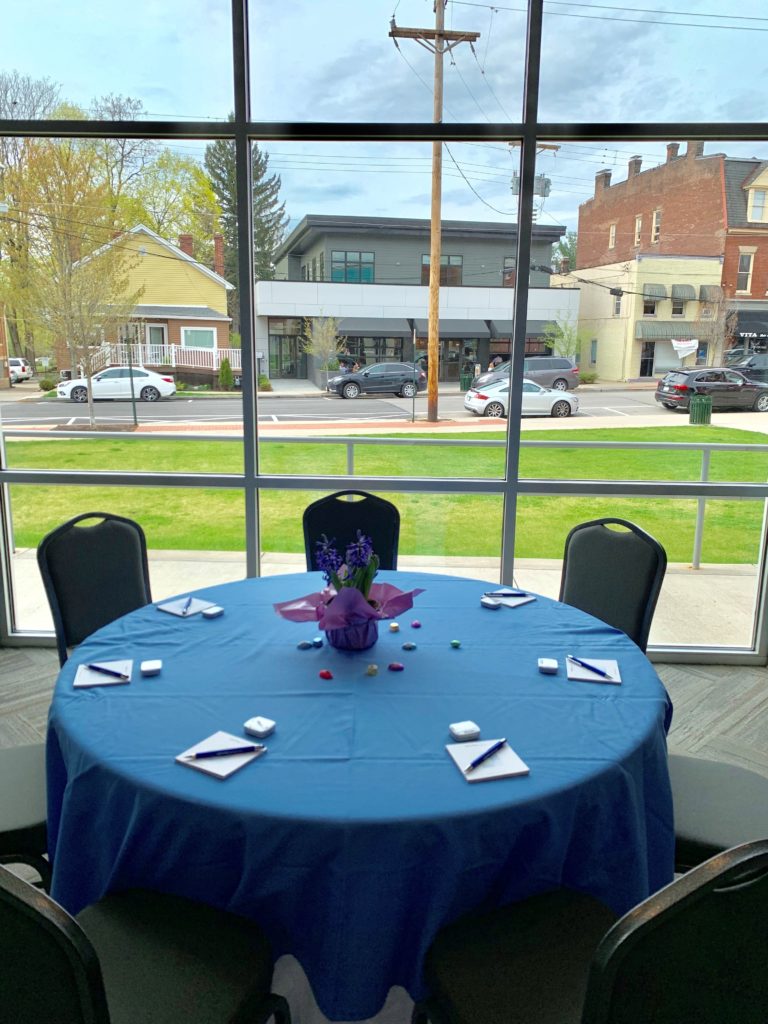
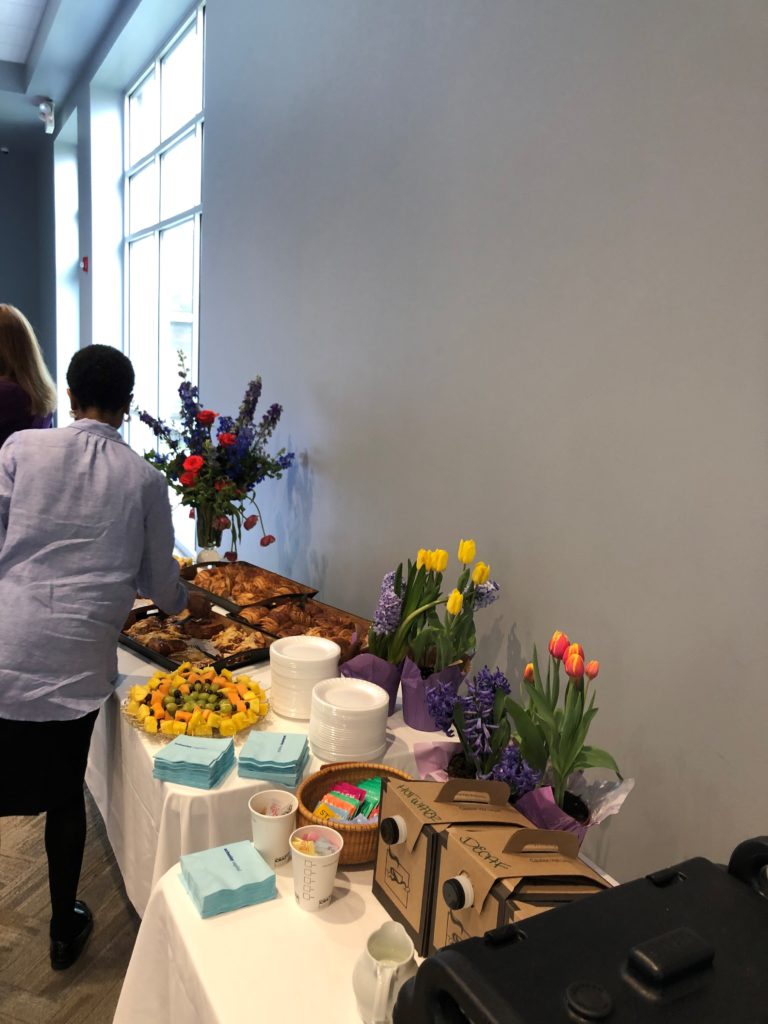
Table Spread across the street from Schenley Capital Inc. at the Tull Family Theater

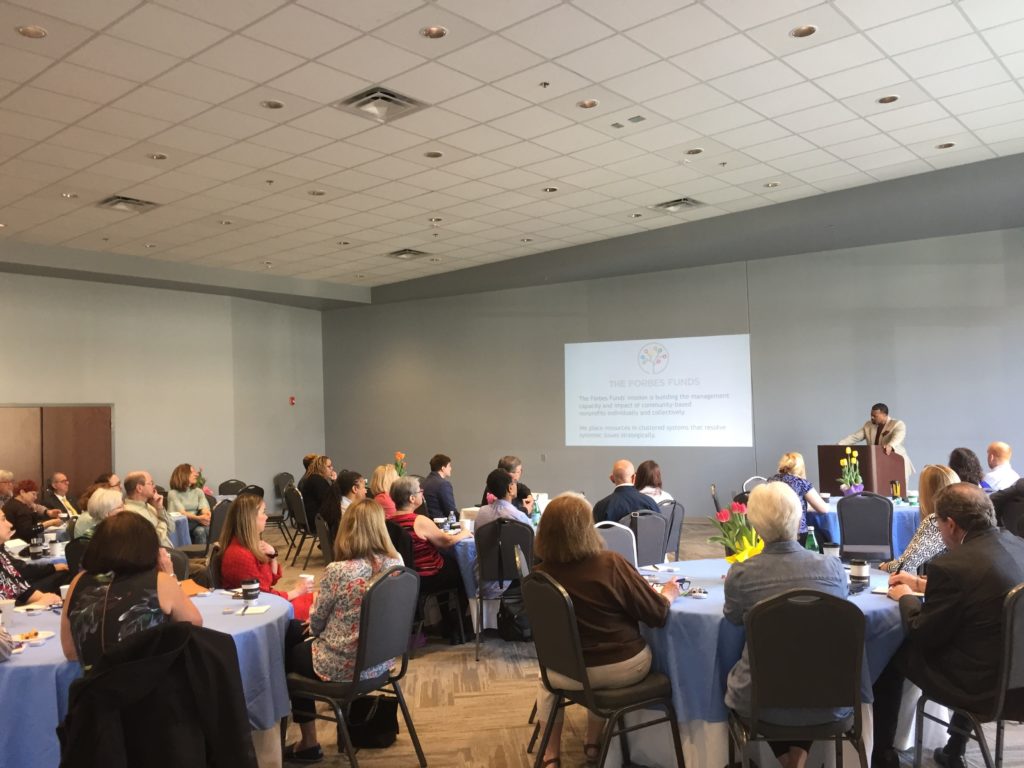
The event took place at The Tull Family Theater in the Esmark and Bouchard Family Community Room; a great location to host an event! Guests nibbled on croissants from Adesso Cafe (La Gormandine), and sipped coffee from Crazy Mocha. There were more than 35 Regional non-profit organizations invited to the event and +50 staff and board members who attended the breakfast.  Sewickley is a town which prides itself on being a giving community— leaders serve on boards and enthusiastically support organizations with varying missions.  The attending organizations ranged from large to small, and the communities represented hailed from Sewickley, Sewickley Heights, Coraopolis, Ambridge, Moon Township, Leetsdale, and Beaver. Many of these organizations work together by promoting other organizations’ services and events. They collaborate and refer specific needs they encounter to the appropriate organization or group.

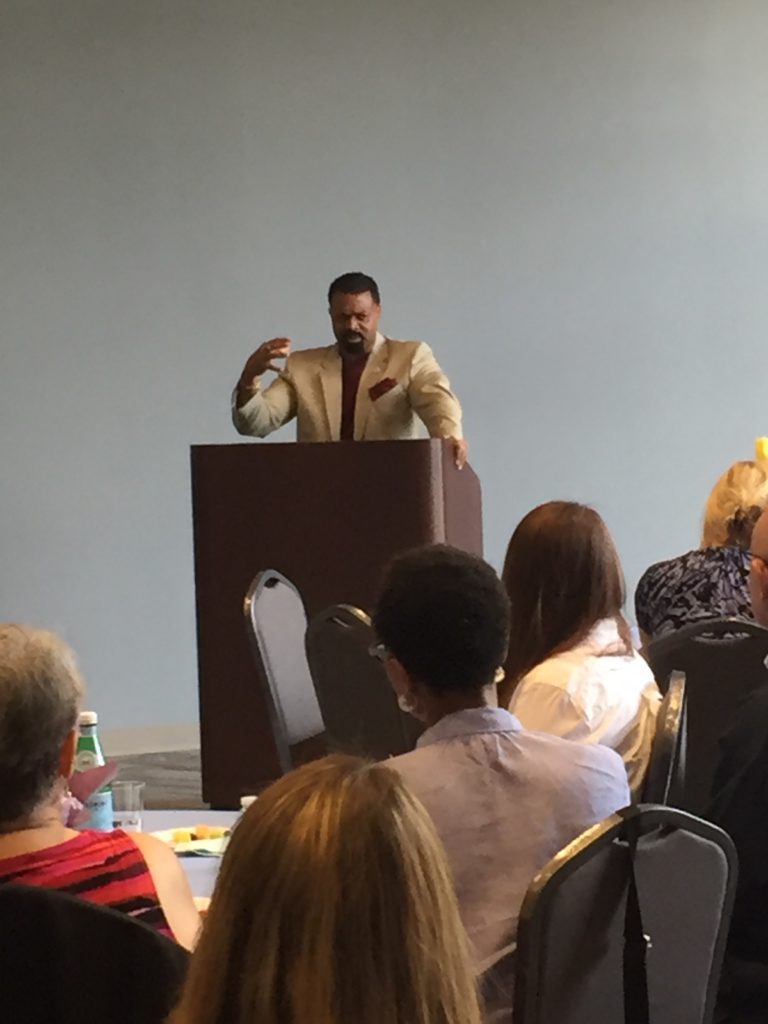
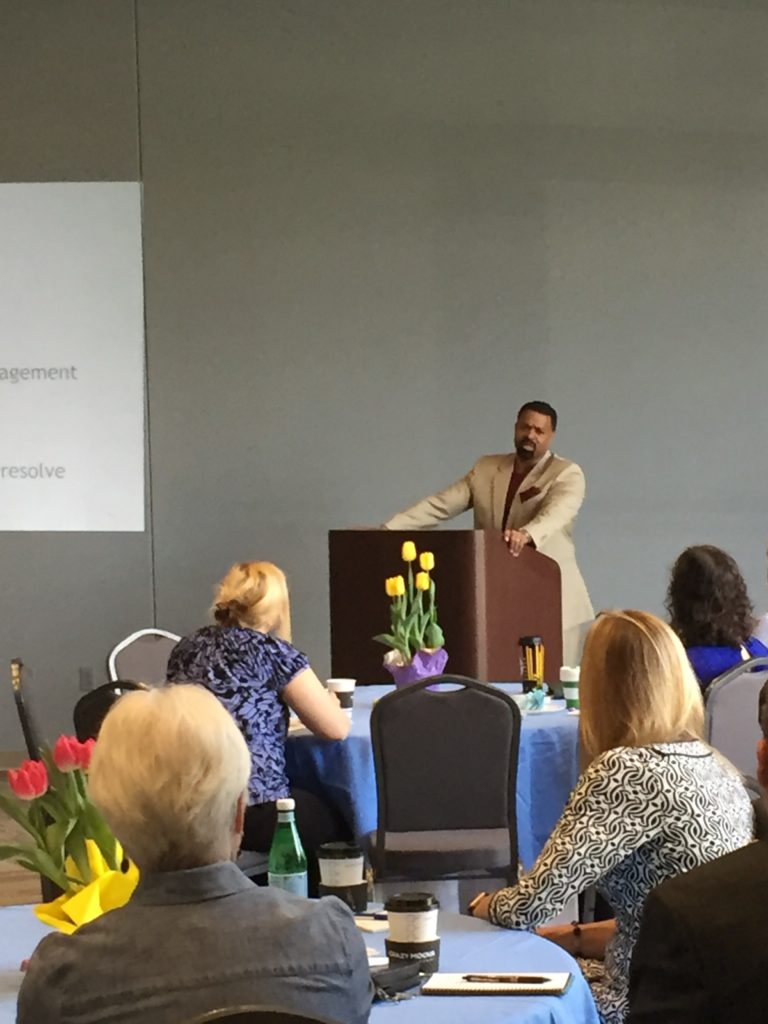
Fred Brown Speaking with enthusiasm to 50+ individuals in non-profits organizations

Fred Brown, President and CEO of The Forbes Funds was the main attraction attendees came to hear. The Forbes Funds’ mission is “building the management capacity and impact of community-based nonprofits individually and collectively”. Fred Brown gave an inspiring and enlightening talk focused on how the number of nonprofits in Pittsburgh have increased over time; but, it’s impact- not so much. He encouraged the SNPC group that their collaboration with one another is a great way to further impact the community by working together toward a common goal, sharing resources, and reducing duplication. He also noted how it is important to think about the longevity of an organization’s mission and how it can be sustained over time with the changing needs of the community. Working together with other businesses and nonprofits is an important part of sustainability and increasing an organization’s impact. His main idea was to be transformational in a transactional world. In being transformational over transactional in how we work toward the betterment of our communities- organizations can shift from good organizations to great organizations. 

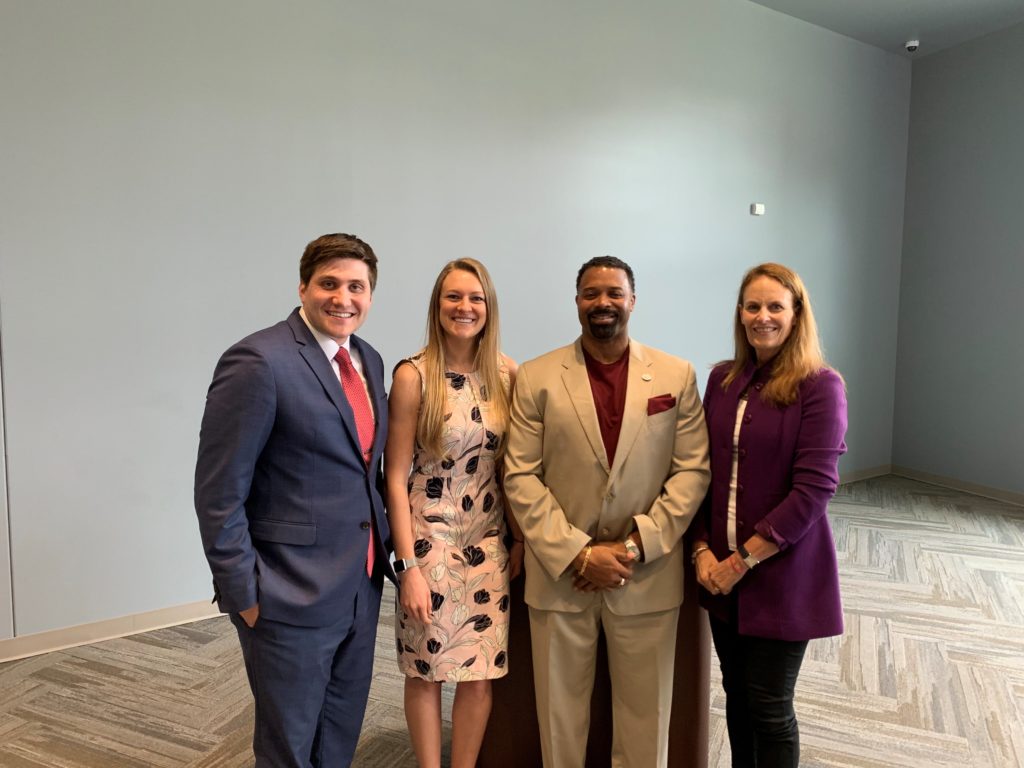
Beth Genter and her associates Lauren Porter and Derek Green look forward to sponsoring next Spring’s event for the Sewickley Non-Profit organizations!

8 Ideas to enhance your Individual Retirement Account! (IRA)

You have until Monday, April 15th, 2019 to make your 2018 Individual Retirement Account contribution.  It is possible you could add to your ROTH IRA or receive a deduction on your Traditional IRA contribution. 

  • 1. Maximize your 2018 IRA contribution—before April 15th

You can place $5,500 into your IRA +$1,000 if you are over 50 years old = $6,500

  • 2. Maximize your 2019 IRA Contribution—you can do this immediately

You can place $6,000 into your IRA and +$1,000 if you are over 50 years old = $7,000

  • 3. Consider a ROTH IRA – ROTH IRA’s have more flexible rules

You can contribute to a ROTH if you are under these limits:
Single filer and you make less than $137,000. Phase out starts at $122,000.
Married filing jointly and you make less than $203,000. Phase out starts at $193,000.
You DO have to pay taxes when you contribute to your ROTH IRA
You will NOT receive a tax deduction
You will NOT have to pay any taxes when you take the funds out at the time of your retirement
You can take out funds after 5 years without paying the 10% early withdraw penalty, such as a 1st time home purchase

  • 4. Consider a Traditional IRA – you may qualify for a tax deduction

You are single and make less than $63,000 – $73,000
You are married and make less than $103,000 – $123,000

  • 5. How can I invest my IRA savings?

You can invest in individual stocks, mutual funds, bonds or ETF’s (exchange traded funds)
We would be happy to talk with you about your IRA investment selections
Structuring your portfolio for long term growth is important

  • 6. Consider the fantastic advantages of an IRA!

Your money grows without paying capital gains tax or income tax on your dividends and income
Your money compounds and grows over the years – very powerful!

  • 7. Minimize Fees and Expenses in your IRA Account

Choose an account with inexpensive trading fees – we work with Schwab Institutional = $4.99 per trade
Choose a Schwab account – No annual account fees
Choose inexpensive no-load mutual funds for broad diversification – US large companies, US small companies, European large companies and a mix of bonds to invest your IRA funds

  • 8. You could initiate an IRA for your spouse even if they do not work outside of the house

Rush to make your Individual Retirement Account contribution this year and every year.  An IRA account is one of the most powerful investment vehicles because of the tax-free nature of this account.  Most importantly, your money grows and compounds over time. 

We at Schenley can guide you through the process!

Worried about the current Volatility?? Think big Picture…

The Big Picture:

• The diversified approach will ward off the effects of the current volatility
• Late year sell-off has created attractively priced US Equities
• This is the longest expansion in history – 113 months from June 2009

There were three .25-point Federal Reserve (FED) rate hikes in 2018 – heated trade squabbles between the US and China which commanded investor attention. The emerging markets slow-down in China, which influenced and spread to other emerging market economies. This volatility expanded from the emerging markets to the developed markets affecting equity and bond markets. Rising interest rates and fears of slowing earnings growth fueled a sharp decline in US equities, that began in early October.

Will the FED continue to raise rates?

This week all eyes are on the FED, waiting to see if the FED will announce their last rate hike for 2018. We think the FED will not raise rates in 2018, due to the recent market volatility. We do believe that the FED will tamp on the breaks in 2019 and be slow to raise rates. Although we do believe that the market and the economy will be able to withstand 2-3 rate hikes in 2019. The hard-economic data signals continued strength in the US labor market and industrial production are “reasonably” strong. Inflation is moderate and there seems to be no further changes on the horizon. The FED is still on the path of “normalizing” rates as they have been very open to announce and communicate their intension to raise rates, although there might be a pause in this strategy.

Are we in Mid-Cycle or Late -Cycle rally?

This argument has been going on for the last several years; we may be in the 7th or 8th inning or more mid-market cycle. In the wake of the 2008 crisis leverage was decreased, corporate cash was at very low levels, and corporate debt was very high, hence there was no strength or cushion in the corporate balance sheets. Currently, companies are stronger, have higher amounts of cash not so much corporate debt and banks have higher reserves. Fiscally the economy is doing very well, economic fundamentals remain strong and solid.
For 21 months the growth stocks lead the market. In the past five years the S & P Index returned 11%! After such an up-turn the market usually goes into a corrective phase, which we have experienced in October and November; this type of market decline is not unusual. The leadership of the equity markets has been narrow, as a few stocks lead the market, there has been a change from the big-cap Tech stocks – the FAANG (Facebook, Amazon, Apple, Netflix and Google) stocks in favor of more defensive type of stocks, such as the utility or consumer staples, such as Home Depot or Pepsi. Although, today the market has rebounded and is up +239 points.

Looking ahead….to 2019

Economic fundamentals in the United States remain solid. US Stocks are still relatively cheap on a long-term basis – corporate earnings grew at 25% with the help of the 2017 US tax reform package along with the Trump administration’s push for deregulation. Those factors were positive for economic Growth and corporate profits.
We remain positive for the market to return mid-single digit earnings growth in 2019. It is the precise reason why our portfolios remain fully diversified in the equity sectors and the fixed income sectors to protect our client’s assets. Our bond portfolios are very short term to ensure our portfolios keep up with rising rates. After two years of virtually no volatility, we believe that the current market volatility will continue in 2019. We have introduced several investments to dampen the effects of volatility.

In the 2nd half of December we encourage:

• Gifting for tuition and to family members – Each individual can give $15,000 to each family member
• Contributing to your IRA’s and 529
• Using your Required Minimum Distribution from your IRA – to gift to charity rather than paying income tax on the amount
• Perhaps initiating a Donor Advised Fund at The Pittsburgh Foundation

We would be happy to discuss our market and gifting thoughts
Happy Holidays & a Prosperous New Year from our Schenley family to yours!!

8 Tips to Boost the Value of Your IRA

A Traditional IRA (Individual Retirement Account) allows you to defer income tax
on the money you set aside for retirement. This Individual account is separate
from your 401(k) at work. Your IRA account is NOT tied to your job, so you can
maintain the same IRA account throughout your career.

Here is how to maximize the value of your IRA account:

1)Maximize your tax deduction
You can put $5,500 into your IRA account each year and $6,500 if you are +50
The amount of income you make depends on the amount you may deduct

2) April 17,2018 is the deadline for your $5,500 2017 contribution.
Although as of 1/1/2018 you can make your 2018 IRA contribution any time during the year
The earlier you place $5,500 into your IRA the more time your money can grow & compound

3) Contribute to each spouses account
Married couples can contribute $11,000- $13,000(+50)– if only one spouse is working, the
working spouse can contribute to their account and into a separate IRA account for the
non-working spouse

4) How should I invest my IRA savings?
You can invest in individual stocks, mutual funds, bonds or ETF’s -exchange traded funds
You have many more choices than you do in your 401(k)

5) Even if you do not qualify for a tax deduction –
Your IRA is a great way to save for your retirement
You must have earned income from your job
You must be younger than than 79 ½
Single filers: you must make less than $62,000-$72,000 to take a tax deduction
Married filers: You must make less than $99,000-$119,000 to take a tax deduction

6) Consider the fantastic advantages of an IRA
Money grows without paying capital gains tax – a tax on the gain on your investments
Money grows without paying tax on the income generated by income or stock dividends

7) Minimize Fees
Choose Large & small company, US, European, Real Estate and a mix of bonds for your IRA
Choose no load or inexpensive mutual funds for your IRA Account
Choose an account with inexpensive stock trading fees
Choose an account such as a Schwab account, which does not have annual account fees

8) Consider a ROTH IRA – as the ROTH has more flexible rules
You do pay the tax up front for the ROTH IRA account
You do not receive a tax deduction
You do not have to pay any taxes when you take the funds out at the time of your retirement
You can take out funds after 5 years with out paying a 10% penalty, such as a 1st time home
buyer

Rush to make your IRA contribution this year and in every consecutive year. An IRA
account is one of the most powerful investment vehicles because of the tax-free
nature of this account; and the fact that your money compounds and grows over
time. We at Schenley Capital are available to guide you through the IRA process or
assist you with your IRA investments. There are many ways to invest your IRA to
maximize the value of your IRA for your future!

European Large Cap

European Large Cap companies are European companies that are valued at 10 billion and above. To learn about how that valuation is calculated, visit our blog on large cap. The next question may be, what qualifies as a European company? Is it developed companies in the European region? Does that include Switzerland and the UK or is it just the “Eurozone”? Each mutual fund groups companies together differently, while some may include 300 large companies from 17 European countries, others may hold 50 big European companies focused only in countries using the euro. The developed market European large-cap funds are drastically different from each other and vary in more measures than how US large cap companies are chosen. Some examples of European Large Cap stocks are Nestle (NSRGY) the largest and well-known food and beverage company in the world, France Telecom (FTE) the leading telecommunications service provider in France and neighboring countries, Royal Dutch Schell (RDS.A) one of the largest energy companies in the world, and Covidien (COV) a Dublin, Ireland-based company that develops, manufactures, and distributes medical devices, pharmaceuticals, and other health-care products worldwide.

Investing in high quality European companies diversifies and spreads out the risk in your portfolio. It is wise to invest in strong large global companies with solid balance sheets outside of the U.S. Do you have a good portion of non-U.S. investments in your portfolio? As global markets shift, it could be a good idea to keep diversification in your portfolio through a balance of emerging markets or European based investments.


written by: ||lauren pearce, associate||

So what’s a SEP?

A Simplified Employee Pension (SEP) is a practical retirement plan which can be used by small businesses and sole proprietors.  The plans are easier to establish than qualified plans and have practically no filing requirements.  The SEP uses an IRA account as the vehicle for the contributions; the plans do not have complicated trust accounting for the plan sponsor.


The SEP is not a qualified plan, is has unique rules that are different than qualified plans.  For example, SEP’s have more liberal participation requirements than qualified plans, have a later initial starting date and have different contribution, distribution and vesting rules.


Why a Simplified Employee Pension?  (SEP)

  • Can contribute up to 25% of compensation or a maximum of $54,000 – whichever is less – No catch-up – No Elective Deferrals
  • Contribution is tax deductible as a business expense for the company
  • Completely flexible annual contribution amounts – Co. is not required to contribute every year
  • Minimal administration – do not file any IRS documents (tell your accountant about the amount of your contribution)
  • Do not have to employ an actuary
  • Follows the IRA rules for loans, distributions, penalties…(no loans)


Steps for Business to establish a SEP

  • Company sets up a master account at Schwab ( no extra legal documents for the company – Schwab provides the  documentation)
  • Employer informs Employee’s that SEP has been initiated
  • Employees receive information – disclose that the return is not predictable
  • User friendly access for employees – All is on-line with Schwab
  • Schenley will meet with individuals alone to discuss risk tolerances, goals…
  • Company could contribute a Dollar amount or a % of salary


Participation Restrictions if the Employer chooses to exclude:

  • Sponsor must provide to all employees (including part time)
  • 21 years of age
  • Worked as an employee 3 of the last 5 years
  • Received at least $550 during the year.


Who is excluded?

  • Covered by a Union agreement if their retirement benefits were bargained for by union and their employer
  • Non-Resident Aliens who have no U.S. source of earned income from employer


When to establish?

  • Established and Funded the date of the Federal Tax return filing or extension


Who can establish a SEP and by what date?

          Who                                        Latest Date

          Sole Proprietorship                  4/15/16 or 10/16(Extension date)

          Partnership  or LLC                  4/15/16 or 10/16

          Corporation                             3/15/16 or 9/16

          S – Corporation                        3/15/16 or 9/16


Steps for establishing a SEP-IRA with your Employees:

  • Execute a Written Agreement to provide benefits to all eligible employees
  • Give employees certain information about the SEP & Agreement
  • Set up a SEP-IRA for each employee
  • Employees can roll the IRA into a ROTH IRA – must pay tax 1st


written by: ||elizabeth genter, schenley president||

Ten Tax Lowering Tips

Some will save you time & money when preparing your taxes returns. Other strategies will help you avoid costly penalties and interest on your Federal & State taxes. 

These tips will help you lower your blood pressure while keeping more money in your pocket!


1.) Contribute to your Individual Retirement Accounts – IRA’s

If you haven’t contributed to your retirement account for 2017 

Do so before the April 17, 2018 deadline

  • You can put away $5,500 if you are below 50 Yrs. old
  • You can put away $6,500 if you are +50 yrs. Old


2.) Maximize your pension contribution

  • Pension contributions are in pre-taxed dollars.
  • All pension assets grow tax- deferred


3.) Organize your records for Tax time

  • W-2’s and 1099’s, last year’s tax return, list of charitable contributions 
  • Use tax organizing software – it will help you to print out useful reports with a click


4.) Did you know you can use your RMD for gifts?

  • Your required minimum distribution can be given to your church, for gifts to a school or arts organization and you don’t pay the ordinary income tax on those funds.


5.) Itemize your tax deductions

  • Worth the trouble – you can save Thousands in deductions
  • Deduct mortgage interest
  • Charitable deductions
  • Miscellaneous deductions – Tax preparation, Investment Advisory fees, job hunting expenses & home office


6.) Use the Home Office Deduction

  • The eligibility rules have loosened up for the home office deductions


7.) Why not start a 529 account for college education

  • You can contribute up to $14,000 a person as a parent or grandparent


8.) File and Pay your taxes on time

  • If you can’t finish your return – you must pay your taxes by 4/17/2018
  • You can file for a 6 Mo. Extension – 10/15/ 2018


9.) File Electronically

  • IRS processes these faster than a paper return
  • You will receive your refund typically within 21 days!


10.) Decide 

  • You may need help with your investments and your return!


Written by: ||elizabeth genter, schenley president||

IRA Contributions Can Benefit You at Tax Time

The 2017 tax season is almost here. Like everyone else, you want to take advantage and receive the highest amount of deductions possible, getting the best refund back! But, where to start? One great way to take advantage of tax season is contributing to your IRA account. You can make contributions throughout the year into your IRA or you can make a single lump sum contribution before the tax deadline on 04/17/2018 (for the 2017 tax year). So, how do you know how much you can contribute?

For the 2017 tax year, you can contribute up to $5,500.00 to your IRA if you are under the age of 50 years old. Once you turn 50, you can contribute $6,500.00 to your IRA yearly without taking an excess contribution penalty for the year. This rule allows those who are closer to retirement to “catch up” and add more to their IRA. Once you reach 70 ½ years of age, you cannot make contributions to your IRA anymore, although if you have a Roth IRA, you can still contribute. After making the smart choice to contribute to your IRA yearly, before filing your taxes; you may be wondering what tax deductions you may receive.

There are two scenarios that can apply to you and your household. The first scenario is employer provided retirement plans. If your employer provides you with a retirement plan at work- that is fantastic! This does not mean you shouldn’t have your own IRA account independently from work as well. You can potentially take advantage of tax deductions each year from your personal IRA. Any contributions made to an employer sponsored retirement for the year are not tax deductible. If you or your spouse, if you are married, have an employer sponsored retirement plan, then your Modified Adjusted Gross Income (MAGI) will determine how much of deduction amount you can claim for your IRA, if any. Your accountant will have the limitations on income for the year that will still allow you to claim a deduction on your IRA contributions. The second scenario is if neither you or your spouse’s employer, if you are married, offer a company sponsored retirement, you may take a full deduction on your taxes for any contributions made that year. Again, you should speak with your accountant for the exact income limitations for each scenario.


If you do not have an IRA account, you should consider opening one today.

Not only are there potential tax deductions that you can benefit from yearly,

you will also benefit from compounding interest and planning for your future!


Written by: ||cassandra hartman, office manager||